UK Online Gambling Sector Shows Resilience Following Remote Gaming Duty Increase
Analysts tracking the UK gambling landscape have reported that major operators maintained solid momentum in the second quarter of 2026 despite the April doubling of Remote Gaming Duty from 21 percent to 40 percent, and this outcome has drawn attention from industry observers monitoring tax policy effects across licensed platforms.
Tax Change Details and Initial Market Response
The duty adjustment took effect in April 2026, applying to all remote gaming activities including online slots, casino games, and bingo products, while the review conducted by Regulus Partners examined six leading operators that together account for roughly 66 percent of UK market revenue. Online betting volumes stayed broadly flat during Q2, yet online gaming revenue advanced by approximately 12 percent over the same period, and several listed companies including Entain, evoke, and Super Group recorded positive UK growth across both the quarter and the first half of the year.
Those figures emerged from detailed performance data compiled in the months after the rate change, and they indicate that immediate revenue pressure has not yet translated into visible contraction for the largest players. The analysis covers results reported through July and August 2026, providing an early snapshot of how operators absorbed the higher tax burden while consumer demand held steady in key product verticals.
Company Performance Highlights
Entain reported continued expansion in its UK gaming division during Q2 and the first half, with growth attributed to product innovation and player retention strategies that offset the elevated duty rate. Evoke similarly posted UK revenue gains across the reviewed periods, while Super Group demonstrated comparable resilience through its core gaming offerings. Together these operators, along with three additional major firms included in the Regulus sample, illustrate a market segment that absorbed the tax increase without immediate disruption to top-line figures.
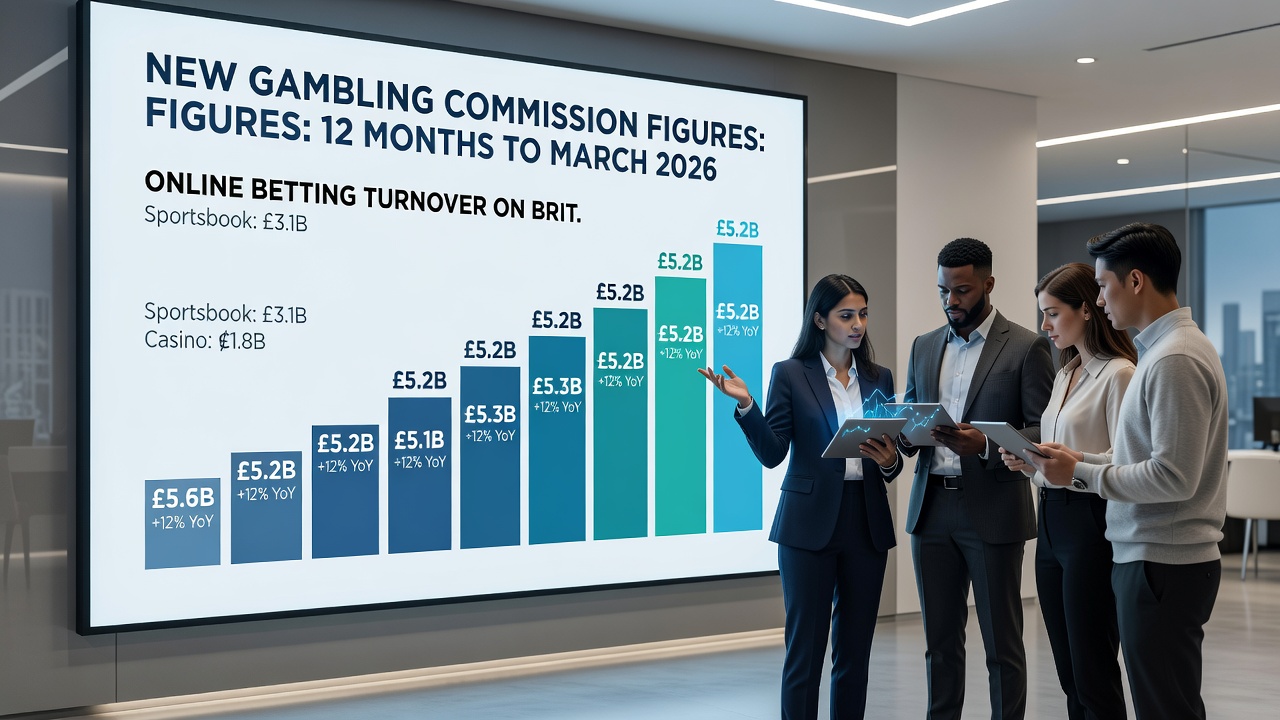
Betting activity, by contrast, showed little movement quarter on quarter, and this divergence between betting and gaming performance highlights differing demand patterns across verticals. Gaming products appear to have sustained player engagement levels that supported revenue growth even after the duty rose, whereas sports betting volumes remained essentially unchanged despite the same tax environment.
Analyst Observations on Timing and Future Impact
Regulus Partners noted that larger effects from the duty increase could surface in subsequent quarters as operators adjust pricing, marketing spend, or product mixes, and the current data reflects only the initial response window. The consultants reviewed operator filings and internal metrics to reach these conclusions, and they emphasized that six months of post-increase trading provides a useful but incomplete picture of long-term adaptation. Operators may yet implement further measures to protect margins once the full annual impact becomes clearer in later reporting periods.
Data compiled through August 2026 shows that the market has maintained overall stability so far, with no widespread evidence of reduced player activity or operator exits from the UK-licensed sector. This early stability aligns with the sample representing two-thirds of total revenue, suggesting the trend extends across a substantial portion of the regulated market.
Market Context in Mid-2026
By August 2026 the duty change had been in place for four months, and quarterly results released during the summer provided the first comprehensive view of operator performance under the new rate. The 12 percent gaming growth figure stands out because it occurred against the higher tax backdrop, and it indicates that gross gaming revenue expanded sufficiently to cover the additional liability while still delivering net gains for the sampled companies. Betting remaining flat suggests that sports wagering demand has not accelerated or declined materially in response to the tax adjustment alone.
Those monitoring the sector continue to watch for shifts in player behavior or promotional activity that might emerge once operators complete their first full year under the revised duty structure. The Regulus review serves as one reference point among several analyses tracking how the 40 percent rate influences investment decisions and product development across UK-licensed sites.
Conclusion
The Q2 2026 results demonstrate that the largest UK operators absorbed the Remote Gaming Duty increase without immediate contraction in gaming revenue, and analysts at Regulus Partners have documented this resilience across operators representing the majority of market share. Betting volumes held steady while gaming advanced, and major companies including Entain, evoke, and Super Group each reported growth through the first half of the year. Further quarters will reveal whether this pattern persists or whether delayed effects begin to appear in operator metrics and market dynamics.